SGB tax 2026

Sovereign Gold Bond redemption tax from April 2026: who still gets it tax-free

By Pratik Bajoria — Chartered Accountant, NISM-certified Research Analyst & Mutual Fund Distributor. Reviewed by Findost desk (CA-led). Published 2026-10-17.

Findost (findost.io) and PaisaGuru by Findost are not affiliated with Findoc, FinDost, or other similarly named brands. PaisaGuru is the AI wealth concierge of Findost.

Direct answer

From 1 April 2026 (Tax Year 2026-27), capital gains on redeeming a Sovereign Gold Bond are tax-free only if you, as an individual, held it from the original issue date until maturity. Premature redemption through RBI (allowed after five years) and bonds you bought on the stock exchange are now taxable. Long-term gains (held over 12 months) are generally taxed at 12.5% plus cess. The 2.5% yearly interest was always taxable at your slab and still is.

Many of my clients bought SGBs because “the gain is tax-free”. For most of them that's still true, but only if they hold to maturity. The Finance Act, 2026 changed the clause behind that belief, and it caught two groups off guard: people planning to use RBI's premature-redemption window, and people who bought older tranches cheaply on NSE.
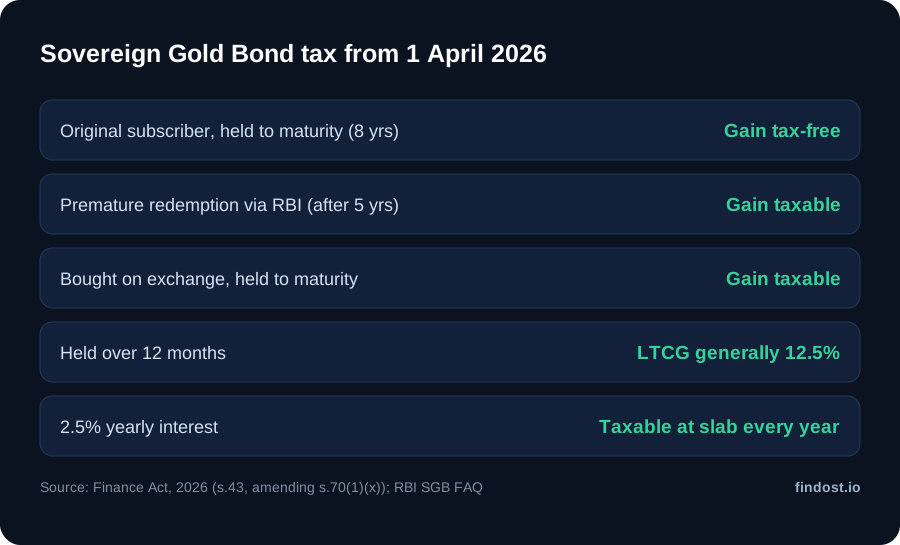
SGB tax from April 2026: gain is tax-free only for an original subscriber holding to maturity; premature redemption via RBI and exchange-bought bonds are taxable; long-term gains generally 12.5 percent; 2.5 percent interest taxable at slab every year.
Summary of SGB tax treatment from Tax Year 2026-27. Source: Finance Act, 2026; RBI SGB FAQ.

What changed in the law

Section 43 of the Finance Act, 2026 substituted clause (x) of section 70(1) of the Income-tax Act, 2025. Redemption of an SGB is now excluded from capital gains only “if held by an individual from the date of original issue till maturity”. Before this, the exemption was read as covering any individual redeeming through RBI, including on premature redemption.

SGB tax treatment by case, Tax Year 2026-27
Your caseGain on redemption / saleInterest (2.5% a year)
Bought at original issue, held to maturity (8 years)ExemptTaxable at slab
Bought at original issue, premature redemption via RBI (after 5 years)Taxable capital gainTaxable at slab
Bought on NSE/BSE, held to maturityTaxable capital gainTaxable at slab
Sold on the exchange before maturityTaxable capital gain (as before)Taxable at slab

Sources: Finance Act, 2026 (Gazette), section 43; Income-tax Act, 2025 as amended; RBI FAQ on Sovereign Gold Bonds.

Illustration: premature redemption vs holding to maturity

Illustration with assumed prices (not an actual tranche): you subscribed to 20 grams at ₹3,000/gram, and the redemption price works out to ₹12,000/gram.

Illustrative SGB redemption tax
Premature redemption (year 6)Held to maturity (year 8)
Capital gain₹1,80,000₹1,80,000
Tax on gain (12.5% + 4% cess)₹23,400Nil
Yearly interest (taxable at slab)₹1,500₹1,500

In this illustration, waiting two more years saves about ₹23,400 in tax. Whether waiting suits you depends on the gold price risk you're willing to carry and your need for cash. The tax is only one input.

How the redemption price and windows work

  • The redemption price is the simple average of the closing price of 999-purity gold published by IBJA for the three business days before the redemption date (RBI FAQ).
  • Premature redemption is allowed only on interest dates after five years. RBI publishes a calendar with the window to submit requests; see the April–September 2026 calendar.
  • No TDS is deducted on SGB interest or redemption, so report both in your return yourself.

For the new section numbers referred to here, see the Income-tax Act 2025 section mapping. For how much gold belongs in a portfolio at all, read the asset allocation guide.

Related on Findost

FAQ — answered simply

Is SGB redemption still tax-free in 2026?

Only in one case. From 1 April 2026, capital gains on redemption are exempt if an individual held the bond from the date of original issue till maturity (Finance Act, 2026, amending section 70(1)(x) of the Income-tax Act, 2025). Premature redemption and bonds bought on the stock exchange do not qualify.

How is premature SGB redemption taxed now?

The gain (redemption price minus your cost) is a capital gain. If you held the bond for more than 12 months it is generally long-term and taxed at 12.5% plus cess; otherwise at your slab rate. Check the current Act for your facts.

I bought SGBs on the NSE or BSE. Is maturity tax-free?

No. The exemption now needs holding from original issue, so a bond bought in the secondary market is taxable even if held until maturity.

Is the 2.5% SGB interest taxable?

Yes. The yearly interest has always been taxable at your slab rate under 'income from other sources'. No TDS is deducted, so include it in your return.

How is the SGB redemption price set?

RBI uses the simple average of the closing price of 999-purity gold published by the India Bullion and Jewellers Association for the three business days before the redemption date.

Next step

Finished reading — want this for your situation?

A short WhatsApp wealth / portfolio check helps map goals, overlap and hygiene questions. Education first; personalised recommendations escalate to a human advisor.

Official channel: WhatsApp +91 62052 47092 · Educational intake, not a buy/sell call.

WhatsApp check

Or browse free calculators, PaisaGuru, and the FAQ.

YMYL / educational caveat: this guide is general financial education for India, not personalised investment, tax, or legal advice, and not a solicitation to buy or sell securities or insurance. Mutual fund and securities investments are subject to market risks; read all scheme-related documents carefully. Past performance is not indicative of future returns. Tax, exit-load and product rules can change — verify with official sources or a qualified professional before acting. PaisaGuru by Findost escalates personalised recommendations to a human NISM-certified advisor. Findost (findost.io) and PaisaGuru by Findost are not affiliated with Findoc, FinDost, or other similarly named brands. PaisaGuru is the AI wealth concierge of Findost.