Direct answer
A Direct Plan is bought straight from the fund house (or an execution-only platform) with no distributor in the chain. A Regular Plan is bought through a mutual fund distributor, bank or broker, and its expense ratio includes the distributor's commission. Same scheme, same portfolio, same fund manager — only the cost and the NAV differ.
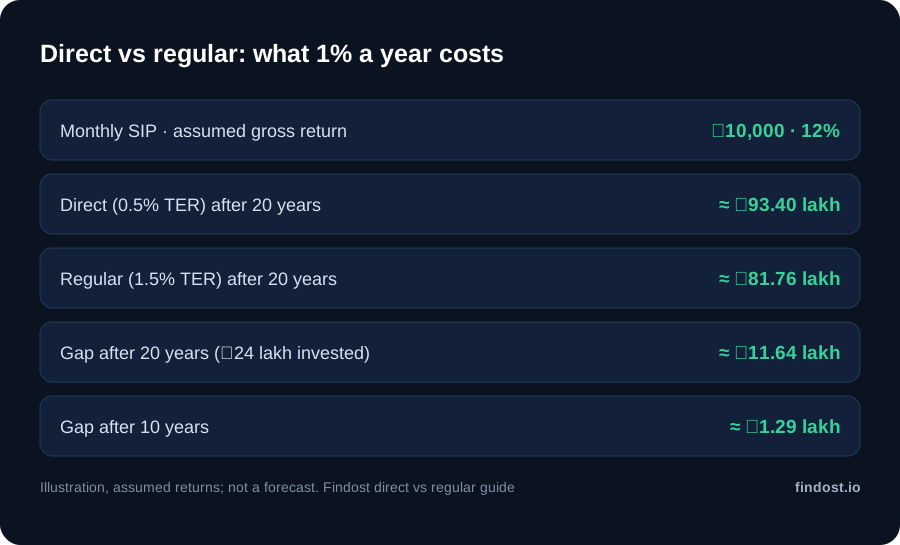
On a ₹10,000 monthly SIP for 20 years at an assumed 12% gross return, a 1-percentage-point higher expense ratio (1.5% Regular vs 0.5% Direct) leaves about ₹11.6 lakh less at the end — on ₹24 lakh invested. Whether that is worth paying depends on the service you receive. Educational content from Findost / PaisaGuru by Findost; we are not Findoc or FinDost.
If you switch from Regular to Direct, it's a redemption and a fresh purchase, so capital gains tax can apply. For equity funds, long-term gains now sit in section 198 of the Income-tax Act, 2025 (old 112A); the old-to-new section mapping lists the rest.
What is a regular mutual fund plan?
When people search for a “regular mutual fund”, they usually mean the Regular Plan of a scheme. Every open-ended scheme in India has two plans. Since 1 January 2013, SEBI has required fund houses to offer a separate Direct Plan for investments not routed through a distributor, with a separate NAV and a lower expense ratio because no distribution commission is paid from it (SEBI circular, September 2012). The Regular Plan pays an ongoing trail commission to the distributor (identified by an ARN — AMFI Registration Number) out of the scheme's expenses.
Direct vs regular mutual fund: what is the same, what changes
| Feature | Direct Plan | Regular Plan |
|---|---|---|
| Portfolio & fund manager | Same | Same |
| Expense ratio (TER) | Lower — no distribution commission | Higher — includes distributor trail |
| NAV | Higher over time | Lower over time |
| How you buy | AMC website/app, MF Central, execution-only platforms, via a fee-paid RIA | Distributor, bank, broker acting as distributor |
| Who does selection & monitoring | You (or an adviser you pay separately) | Distributor-led service, paid through TER |
| Risk, Riskometer, exit load, tax | Same as the scheme | Same as the scheme |
SIP regular vs direct: ₹10,000 per month cost gap
Illustration: ₹10,000 SIP, 12% assumed gross return, Direct TER 0.5% vs Regular TER 1.5% (net returns 11.5% vs 10.5%). These are round illustrative expense ratios, not quotes for any scheme. For actual figures, our regular vs direct TER gap 2026 study found a median gap of 0.785 percentage points across India's 50 largest active equity funds (AMFI TER data, 30 Sep 2026).
| Years | Invested | Direct corpus | Regular corpus | Gap (% of direct) |
|---|---|---|---|---|
| 5 | ₹6,00,000 | ₹8,13,572 | ₹7,91,555 | ₹22,016 (2.7%) |
| 10 | ₹12,00,000 | ₹22,55,442 | ₹21,26,594 | ₹1,28,847 (5.7%) |
| 15 | ₹18,00,000 | ₹48,10,828 | ₹43,78,276 | ₹4,32,552 (9.0%) |
| 20 | ₹24,00,000 | ₹93,39,666 | ₹81,75,968 | ₹11,63,698 (12.5%) |
| 25 | ₹30,00,000 | ₹1,73,65,999 | ₹1,45,81,167 | ₹27,84,832 (16.0%) |
The gap grows faster than the years because the cost is charged on a growing corpus every day. Run your own amounts in the direct vs regular calculator or the SIP calculator (enter a return net of the expense ratio).
How much does each 0.25% of expense ratio cost?
₹10,000 a month for 20 years, Direct plan net return 11.5%. Corpus lost for different expense-ratio gaps between the Regular and Direct plans:
| TER gap | Regular corpus | Less than Direct |
|---|---|---|
| 0.25% | ₹90,31,952 | ₹3,07,714 |
| 0.50% | ₹87,35,731 | ₹6,03,936 |
| 0.75% | ₹84,50,547 | ₹8,89,119 |
| 1.00% | ₹81,75,968 | ₹11,63,698 |
| 1.25% | ₹79,11,575 | ₹14,28,091 |
Lumpsum: ₹5 lakh in direct vs regular
A one-time ₹5,00,000 at the same assumptions grows to ₹44,10,292 in the Direct plan versus ₹36,83,117 in the Regular plan after 20 years — a gap of ₹7.3 lakh. Lumpsums feel the cost more than SIPs because the whole amount is exposed from day one.
SEBI expense ratio limits in 2026
Under the SEBI (Mutual Funds) Regulations, 2026 (effective 1 April 2026), the ceiling is set as a Base Expense Ratio (BER); statutory and regulatory levies such as GST and stamp duty are charged on actuals on top. Headline ceilings as disclosed in AMC notices:
| Scheme type (open-ended) | Maximum BER |
|---|---|
| Index funds & ETFs | 0.90% |
| Equity-oriented, first ₹500 crore of assets | 2.10% (lower slabs as assets grow) |
| Other than equity-oriented, first ₹500 crore | 1.85% (lower slabs as assets grow) |
Both plans must stay within these ceilings; the Regular plan's TER is higher because it carries distribution commission. Check any scheme's current Direct and Regular TER on the AMFI TER page or the AMC website.
How to tell if your mutual fund is direct or regular
- Open your Consolidated Account Statement (CAS) or AMC statement — the scheme name says “Direct Plan” or “Regular Plan”.
- Regular-plan transactions show a distributor ARN code; direct ones show “Direct”.
- Compare the NAV: the Direct plan NAV of the same scheme is higher.
- While you are in the CAS, count schemes and check overlap. AMFI data show about 4.5 folios per unique investor (how many mutual funds Indians hold) — see how many mutual funds you should have and the fund overlap calculator.
Switching from regular to direct: tax and exit-load checklist
A switch is a redemption from the Regular plan and a fresh purchase in the Direct plan, so it is a taxable event. For equity-oriented funds, gains on units held for 12 months or less are taxed at 20%, and long-term gains above ₹1.25 lakh a financial year at 12.5% (transfers from 23 July 2024 — verify for your year on the Income Tax portal). Practical sequencing many investors discuss with their CA:
- Stop new SIP instalments in the Regular plan and start them in the Direct plan. The debit date barely matters — see the best SIP date study (AMFI data).
- Switch units that are past the exit-load period and held over 12 months first.
- Use the ₹1.25 lakh annual LTCG exemption across financial years where it helps.
- Leave recent units until their exit load and short-term period end.
- Measure the result with XIRR, not CAGR — see XIRR vs CAGR.
When a regular plan can still make sense
Cost is visible; behaviour is not. A distributor who stops you redeeming in a crash, keeps your fund count sensible and handles paperwork for elderly parents can be worth the trail commission. Direct makes most sense when you (or a fee-only SEBI-registered investment adviser) will actually do the selection, rebalancing and annual review. SIPs are a major route into mutual funds — AMFI data show monthly SIP contributions of ₹32,297 crore across 10.02 crore contributing SIP accounts in August 2026 (AMFI monthly data) — so the plan choice on each of those SIPs compounds for years.
Decision checklist
- Do I understand this scheme's objective, Riskometer and costs?
- Who will select and review — myself, a distributor, or a paid adviser?
- What service am I actually receiving for the Regular plan's extra TER?
- Can I stay disciplined in drawdowns without reacting to headlines?
- Before any switch, have I checked tax and exit load in scheme documents?
- Is my emergency fund in place first? (emergency fund guide) And when I need income later, do I have a withdrawal plan (SWP calculator)?
Planning the switch? Check STCG in the equity capital gains calculatorand model a growing direct SIP in the step-up SIP calculator.