NPS withdrawal calculator · 2026 rules
NPS Withdrawal Calculator 2026: How Much Can You Take Out, and What Is the Tax?
By Pratik Bajoria, Chartered Accountant & NISM-certified Research Analyst · Last reviewed 17 Oct 2026 by Pratik Bajoria, CA · Reflects PFRDA exit regulations amended 16 Dec 2025
Since PFRDA moved the lumpsum limit from 60% to 80%, I've had several clients near 60 assume the whole 80% comes out tax-free. It doesn't. The tax exemption still stops at 60% of the corpus, so the extra 20% is added to your income for the year. This calculator shows both numbers side by side, so you can decide how much to take with the tax in view.
Lumpsum in hand after tax (₹)
₹36.9 L
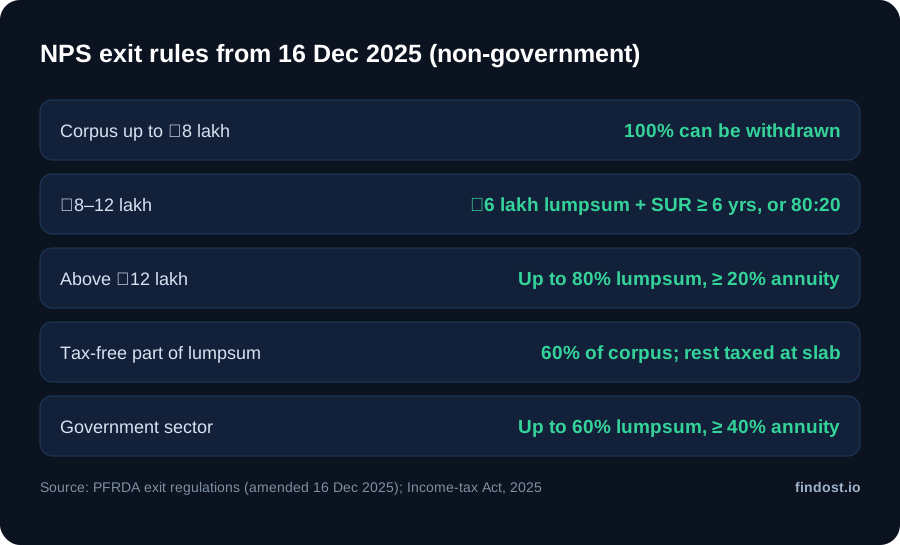
The rules this calculator applies
| Corpus at normal exit | Non-government (All Citizen / Corporate) | Government sector |
|---|---|---|
| Up to ₹8 lakh | Up to 100% lumpsum (or 80:20) | Up to 60% lumpsum, ≥ 40% annuity |
| ₹8 lakh – ₹12 lakh | Up to ₹6 lakh lumpsum + rest via SUR (≥ 6 years), or 80:20 | Up to 60% lumpsum, ≥ 40% annuity |
| Above ₹12 lakh | Up to 80% lumpsum, ≥ 20% annuity | Up to 60% lumpsum, ≥ 40% annuity |
Taxable lumpsum = Lumpsum taken − 60% of total corpus (if positive), taxed at your slab + 4% cess
Sources: PFRDA (Exits and Withdrawals under NPS) Regulations, 2015, as amended; PFRDA press release on key changes (19 Dec 2025); PFRDA exit FAQs for the All Citizen model; tax treatment under the Income-tax Act, 2025. The calculator ignores surcharge and does not model the ₹6 lakh + SUR option.
Worked example: ₹50 lakh corpus, 30% slab (illustration)
| Take 80% | Take 60% | |
|---|---|---|
| Lumpsum | ₹40,00,000 | ₹30,00,000 |
| Tax-free part | ₹30,00,000 | ₹30,00,000 |
| Taxable part | ₹10,00,000 | ₹0 |
| Tax (30% + 4% cess) | ₹3,12,000 | ₹0 |
| Lumpsum in hand | ₹36,88,000 | ₹30,00,000 |
| Annuity corpus | ₹10,00,000 | ₹20,00,000 |
| Pension at an assumed 6.5% (before tax) | ₹5,417/month | ₹10,833/month |
Taking the extra 20% puts ₹6,88,000 more in your hand after tax, but your pension drops by ₹5,417 a month. A smaller corpus works differently: illustration: ₹7 lakh at a 20% slab can be fully withdrawn; ₹4,20,000 is tax-free and about ₹58,240 is tax.
Lumpsum limit and tax by corpus (non-government, 30% slab, maximum lumpsum)
| Corpus | Max lumpsum | Taxable part | Tax (incl. cess) | Annuity corpus |
|---|---|---|---|---|
| ₹8,00,000 | ₹8,00,000 | ₹3,20,000 | ₹99,840 | ₹0 |
| ₹12,00,000 | ₹9,60,000 | ₹2,40,000 | ₹74,880 | ₹2,40,000 |
| ₹25,00,000 | ₹20,00,000 | ₹5,00,000 | ₹1,56,000 | ₹5,00,000 |
| ₹50,00,000 | ₹40,00,000 | ₹10,00,000 | ₹3,12,000 | ₹10,00,000 |
| ₹1,00,00,000 | ₹80,00,000 | ₹20,00,000 | ₹6,24,000 | ₹20,00,000 |
Frequently asked questions
How much can I withdraw from NPS at 60 under the new rules?
For non-government subscribers (All Citizen and Corporate models), PFRDA's amended exit regulations, effective 16 December 2025, allow up to 80% of the corpus as lumpsum, with at least 20% used to buy an annuity. If the corpus is ₹8 lakh or less, all of it can be withdrawn. Between ₹8 lakh and ₹12 lakh there is also an option of up to ₹6 lakh lumpsum with the rest through systematic unit redemption over at least six years. Government-sector subscribers stay at up to 60% lumpsum and at least 40% annuity.
Is the full 80% NPS lumpsum tax-free?
No. The Income-tax Act, 2025 exempts the lumpsum only up to 60% of the total corpus; the tax law was not amended to match PFRDA's 80% limit. Illustration: on a ₹50 lakh corpus, taking 80% (₹40,00,000) leaves ₹10,00,000 taxable; at a 30% slab that is about ₹3,12,000 of tax including cess.
Is the NPS annuity pension taxable?
Yes. Buying the annuity is not taxed, but the pension you receive from it is taxed every year at your slab rate.
What if I exit NPS before 60?
On premature exit, non-government subscribers can take at most 20% as lumpsum and must annuitise at least 80%. If the corpus is ₹5 lakh or less, the whole amount can be withdrawn. Normal exit is available after 15 years in NPS or at age 60, whichever is earlier.
Does this calculator give me a recommendation?
No. It shows the arithmetic of the rules for the inputs you enter. How much to take as lumpsum depends on your other income, health, dependants and how you will invest the money. Confirm current rules with PFRDA or your CRA before exit.
Educational tool only — not investment, tax or legal advice. Figures are formula-based illustrations using the stated assumptions; actual outcomes depend on notified rates, rules and your specific facts. Verify with official sources or a qualified professional before acting. Findost (findost.io) and PaisaGuru by Findost are not affiliated with Findoc, FinDost, or other similarly named brands. PaisaGuru is the AI wealth concierge of Findost.