Direct answer
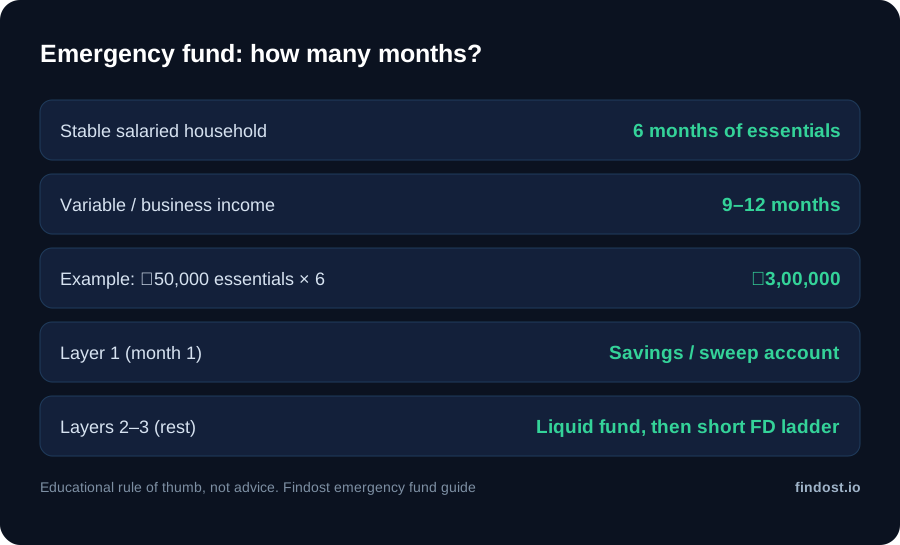
An emergency fund is cash you can reach within a day or two when income stops or an unplanned expense hits — so you are not forced to sell long-term investments or borrow on a credit card at the worst time. A common educational target in India is 6 months of essential expenses for stable salaried households and 9–12 months when income is variable. Example: ₹50,000 of essential monthly expenses × 6 = ₹3,00,000.
Keep it in layers — bank savings / sweep for the first month, a liquid or overnight fund for the next two, and a short FD ladder for the rest. Availability first, return second. This is general education from Findost / PaisaGuru by Findost, not a product recommendation.
One thing I now flag in reviews: don't count Sovereign Gold Bonds as emergency money. They can only be redeemed early in RBI's windows after five years, and from April 2026 that premature SGB redemption is taxable. If you're near retirement, your NPS lumpsum isn't instant cash either; see what the NPS withdrawal tax calculator shows you'd actually get after tax.
What is an emergency fund?
Emergency funds are a dedicated pool of low-risk, high-liquidity money set aside only for genuine shocks: job loss or a gap between jobs, a medical bill beyond your insurance cover, urgent home or vehicle repairs, or supporting a family member. It is not a holiday fund, a down-payment fund or an investment — its job is to keep the rest of your plan (SIPs, NPS, insurance premiums, EMIs) running untouched while you deal with the problem.
How much emergency fund do you need? (India 2026)
Size the fund on essential monthly expenses — rent or home-loan EMI, groceries, utilities, school fees, insurance premiums, other EMIs, transport and medicines — not on your salary. Then pick the number of months from your situation:
| Household situation | Educational starting point | Why |
|---|---|---|
| Dual income, stable salaried jobs | ~6 months | Two incomes rarely stop together |
| Single earner with dependents | 6–9 months | One job loss stops all household income |
| Freelancer, business owner, commission income | 9–12 months | Irregular cash flow and slower recovery |
| Retired / near retirement | 12+ months of expenses not covered by pension | Avoid selling growth assets in a market fall |
These are planning heuristics used in financial education, not regulatory rules. Adjust for job security, health, dependents and any other liquid buffers you already hold. If a home or car loan is part of your essentials, check the exact instalment with the EMI calculator.
Emergency fund calculator
Enter essential monthly expenses, the months of cover you want, what you already have in savings and how much you can set aside each month. The calculator shows your emergency fund target, the shortfall, how many months it will take to close the gap, and a 3-layer split.
Emergency fund target
₹3.0 L
Formula: target = monthly essential expenses × months of cover; months to build = (target − existing liquid savings) ÷ monthly amount set aside. Interest earned while you build is ignored, so the real timeline is slightly shorter.
Emergency fund targets in ₹: quick table
Target corpus = essential monthly expenses × months of cover.
| Monthly essential expenses | 3 months | 6 months | 9 months | 12 months |
|---|---|---|---|---|
| ₹25,000 | ₹75,000 | ₹1,50,000 | ₹2,25,000 | ₹3,00,000 |
| ₹40,000 | ₹1,20,000 | ₹2,40,000 | ₹3,60,000 | ₹4,80,000 |
| ₹60,000 | ₹1,80,000 | ₹3,60,000 | ₹5,40,000 | ₹7,20,000 |
| ₹1,00,000 | ₹3,00,000 | ₹6,00,000 | ₹9,00,000 | ₹12,00,000 |
How long does it take to build an emergency fund?
Worked example: essential expenses of ₹50,000 a month and a 6-month target of ₹3,00,000, starting from zero. Setting aside ₹10,000 a month takes 30 months; ₹15,000 takes 20 months; ₹25,000 takes 12 months. To automate the saving with a fixed monthly deposit, the RD calculator shows what a recurring deposit grows to.
| Monthly saving | 1 month cover (₹50,000) | 3 months (₹1.5 lakh) | 6 months (₹3 lakh) |
|---|---|---|---|
| ₹10,000 | 5 months | 15 months | 30 months |
| ₹15,000 | 4 months | 10 months | 20 months |
| ₹25,000 | 2 months | 6 months | 12 months |
Where to keep emergency funds in India: options compared
| Option | Access | Safety notes | Tax on returns |
|---|---|---|---|
| Bank savings account | Instant (UPI / IMPS / ATM) | DICGC insured up to ₹5 lakh per depositor per bank | Slab rate; 80TTA up to ₹10,000 (old regime) |
| Sweep-in / auto FD | Near-instant (auto-break) | Bank deposit — same DICGC cover | Slab rate |
| Liquid mutual fund | Next business day; instant up to ₹50,000/day where offered | Market-linked (credit & rate risk), low volatility; not DICGC insured | Slab rate (units bought from 1 Apr 2023) |
| Overnight mutual fund | Next business day | One-day securities — lowest rate risk among debt funds | Slab rate |
| Short bank FD ladder | Same day to a few days (premature withdrawal) | DICGC cover; premature-withdrawal penalty is bank-specific | Slab rate |
| Equity funds / stocks | A few business days, but prices can be sharply lower exactly when you need cash | Not suitable for the core emergency sleeve | Equity STCG / LTCG |
Sources: DICGC deposit-insurance FAQs (₹5 lakh cover since 4 Feb 2020); SEBI mutual fund investor FAQs and SEBI's Instant Access Facility rules (₹50,000 or 90% of folio value per day per scheme, liquid schemes only); liquid-fund graded exit load of 0.0070% on day 1 to nil from day 7 as disclosed in scheme documents. Tax: verify slab and debt-fund rules for your year on the Income Tax portal.
A 3-layer emergency fund: ₹3 lakh worked example
- Layer 1 — ₹50,000 in savings / sweep (1 month): same-day UPI access for a hospital deposit or urgent repair, at any hour.
- Layer 2 — ₹1,00,000 in a liquid or overnight fund (2 months): ₹50,000 can come back the same day via instant redemption where offered, the rest the next business day.
- Layer 3 — ₹1,50,000 as three ₹50,000 FDs (3 months): break only the FD you need, so the others keep earning.
With two earners or a larger fund, splitting deposits across two banks keeps more of the money within the ₹5 lakh per-bank DICGC limit.
Is a liquid fund good for an emergency fund?
For the middle layer, often yes: liquid funds hold debt and money-market instruments with short maturities, normal redemptions reach your bank the next business day, and there is no exit load after day 7. But they are not savings accounts — they carry small credit and interest-rate risk, are not covered by DICGC, and the instant-redemption cap means you cannot pull a large amount the same day. Read the scheme's Riskometer and SID, and prefer a Direct plan if you are choosing the fund yourself (the direct vs regular guide explains the cost difference).
Keep your emergency fund in step with inflation
A fund sized for today's expenses shrinks in real terms. At an assumed 6% annual inflation (illustrative — check the latest CPI data from MoSPI), the same 6-month cover costs:
| Years from now | Monthly expenses @ 6% | 6-month target |
|---|---|---|
| Today | ₹50,000 | ₹3,00,000 |
| 3 years | ₹59,551 | ₹3,57,305 |
| 5 years | ₹66,911 | ₹4,01,468 |
| 10 years | ₹89,542 | ₹5,37,254 |
Review the target once a year and after any life change — a new EMI, a child, a job switch — and top it up before increasing SIPs.
Emergency fund vs insurance vs investments
- Health insurance pays for large hospital bills; the emergency fund covers deductibles, non-covered items and income gaps. One does not replace the other — see health insurance basics.
- Term insurance replaces income if the earner dies; the emergency fund keeps the household running in the meantime.
- NPS and PPF are long-term and largely locked — they are not emergency money. Plan them separately with the NPS calculator, and compare returns, lock-in and tax in SIP vs FD vs PPF.
- Equity SIPs are for goals 5–7+ years away. Once the buffer is in place, size them with the SIP calculator, keep the fund count sensible (how many mutual funds, overlap calculator) and track returns with XIRR rather than CAGR.
Emergency fund for salaried employees vs freelancers
Salaried employees often have notice-period pay, gratuity and employer health cover, so 6 months of essential expenses is a reasonable start. Freelancers and business owners face lumpy receipts, GST/advance-tax outflows and no employer cover — 9–12 months is safer, and keeping business and personal buffers separate avoids dipping into tax money. Retirees drawing from a corpus can hold 1–2 years of withdrawals in liquid assets so an monthly SWP (systematic withdrawal plan) does not have to sell equity in a crash.
Common emergency fund mistakes
- Sizing on income instead of essential expenses (or forgetting EMIs and premiums).
- Parking it in equity, small-cap or thematic funds for “better returns”.
- Treating a credit-card limit or a pre-approved loan as the emergency fund.
- Locking everything in a single long FD or in instruments with lock-ins.
- Not refilling the fund after using it — refill before restarting other investments.
- Keeping it all in one bank above the ₹5 lakh DICGC limit.
Building the fund month by month? An RD is a disciplined way to do it. Between jobs, check what you're owed in the gratuity calculator before you plan around it.